The Nine-Month Money Check-Up: Why This Fall Matters More Than Most
Pull up a chair. I'm climbing onto my soapbox for a few minutes, and I'd like you to hear me out.
This year, more than any year I can remember, you need to know where your money is going.
Not roughly. Not "I think it's about…" Actually know.
Gas costs more. Groceries cost more. Everyday prices have crept up across the board. And for a lot of households, paychecks haven't kept pace. When costs climb and income stays flat, that gap has to come from somewhere. Too often, it comes from a credit card.
Here's what concerns me most: I'm talking with more and more people who can't tell me what it costs them to live each month. Smart, successful, capable women. I ask the question, and I get a pause, then a guess.
If you don't know that number, how would you know whether you're on track or quietly drifting off course?
Why Now, Before the Holidays
You have nine months of this year behind you. That's a gift. It's real data — your data — showing exactly how this year has treated your budget.
And you have a narrow window to use it. Once Thanksgiving arrives, the season picks up speed: gifts, travel, hosting, year-end giving. Decisions get made fast, and most of them get made with plastic.
Look at your numbers now, and you walk into the holidays with a plan. Wait, and you walk into January with a surprise.
I'd rather you have the plan.
Step 1: Gather Nine Months of Spending
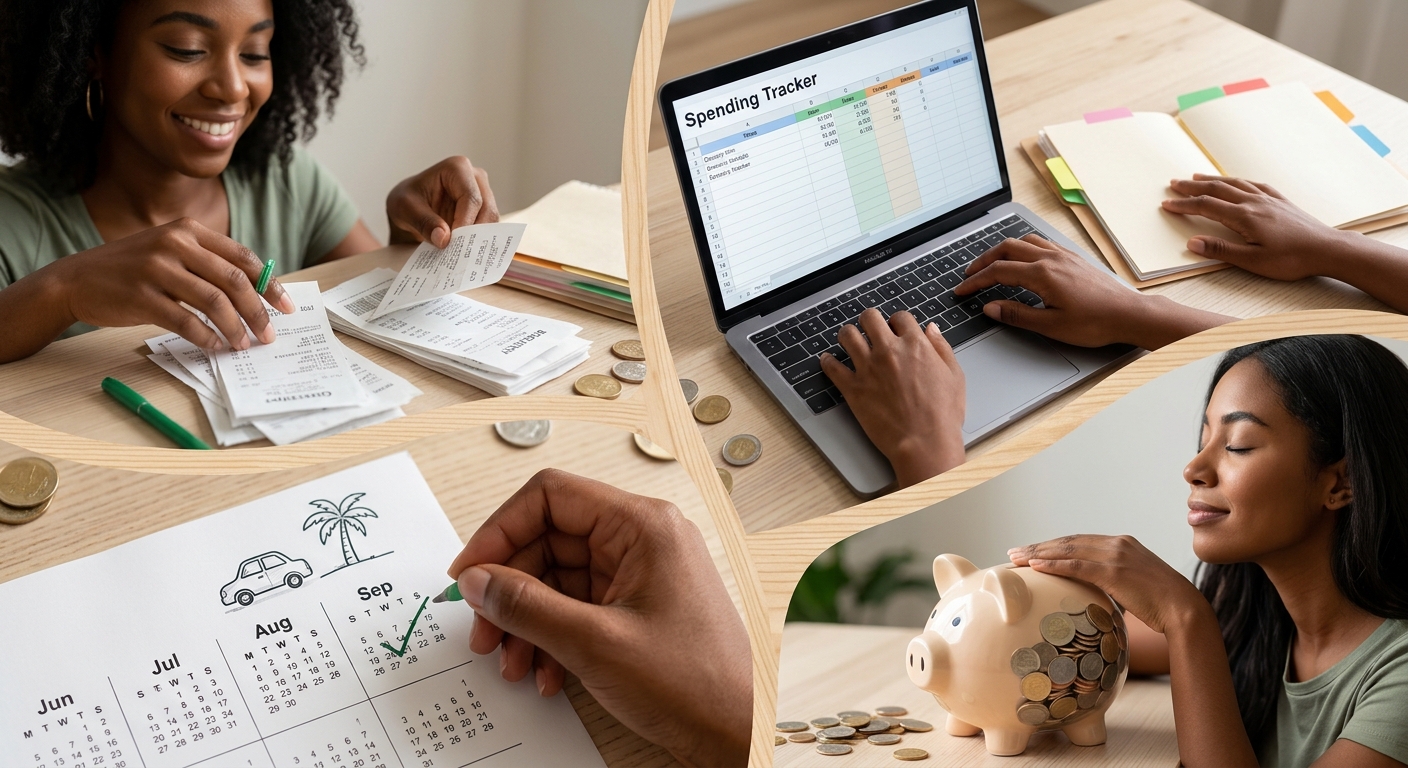
Pull your bank and credit card statements from January through September. Every account. Yes, even the card you only use "once in a while."
If paper statements make your eyes cross, there are budgeting apps — NerdWallet is one — that connect to your accounts and sort your spending into categories automatically. Set it up once, and at the end of each month you'll know exactly what you spent. No shoebox of receipts required.
Step 2: Sort Into Categories
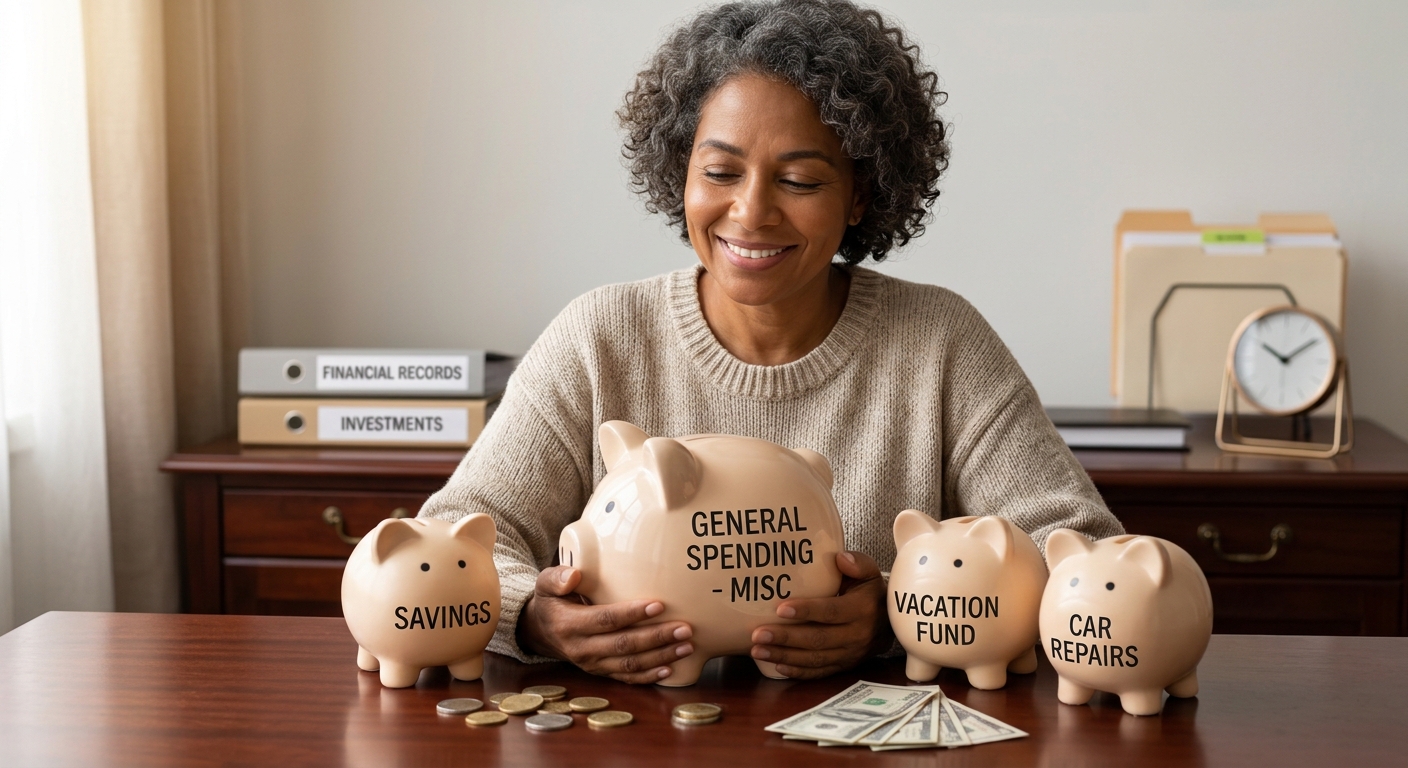
Keep it simple. Something like:
Housing (mortgage or rent, insurance, property taxes, HOA)
Utilities and phone
Groceries
Dining out
Gas and transportation
Insurance and healthcare
Debt payments
Gifts and giving
Travel and entertainment
Subscriptions
Everything else
That last one, "everything else," tends to be the category that tells the truth. Watch it closely.
Step 3: Compare a Typical Year to This Year
This is the step most people skip, and it's the one that matters most.
Look at what a normal month used to cost you. Then look at this year. Where are you over? Where are you under? Where are you way out of whack?
Maybe groceries are running $200 more a month than they did last year. Maybe gas jumped. Maybe dining out slowly doubled because you were tired and busy. (No judgment. I've been there.) Every one of those numbers is telling you something.
Write it down. Document what you're actually spending month to month and, right beside it, what you should be spending. That side-by-side view is where clarity starts.
Step 4: Look at What You Own and What You Owe
Once you know your spending, take inventory:
What you have saved: checking, savings, and any emergency fund
What you owe: credit cards, store cards, car loans, personal loans, home equity lines — anything with a balance and an interest rate
For each debt, write down the balance, the interest rate, and the monthly payment. We'll talk about what to do with that list in the weeks ahead. For now, just get it on paper. Things look a lot less scary once they have names and numbers attached.
Why This Matters So Much as Retirement Gets Closer
If you're within ten or fifteen years of retirement, this exercise carries extra weight.
Your monthly cost of living is the number your entire retirement plan rests on. It shapes how much income you'll need, how long your savings may last, and how much cushion you'll have when life throws a curveball. If that number is a guess, everything built on top of it is a guess, too.
So many of the women I work with worry about outliving their money. That's a real and fair worry. But the first step toward answering it is surprisingly ordinary: know what you spend.
A Little Tough Love
I'll say this kindly, but I'll say it plainly: hoping it all works out is not a plan.
You don't need a finance degree to do this check-up. You need a couple of quiet hours, your statements, and the willingness to look. Whatever you find — better than you feared or harder than you hoped — you'll be making decisions from information instead of worry.
That's worth one afternoon.
Your Next Step
Block two hours on your calendar this week. Gather your statements, sort your categories, and compare this year to a typical one.
When you're ready to turn those numbers into a plan for the life you want, request my complimentary ebook, Build Your Future Blueprint. And if you'd like to talk it through with someone, I'd be glad to meet you on a complimentary 30-minute get-acquainted call.
Get the Free Ebook | Book Your Get-Acquainted Call
This article is for educational purposes only and is not individualized financial, tax, or legal advice. Examples are illustrative and may not reflect your situation..